For many families, a house represents more than property. It may hold decades of memories while also serving as an important financial asset. When an older adult chooses additional daily support, the possibility of selling can add another difficult decision. Fortunately, paying for assisted living without selling a house may be possible through several funding strategies.
The right approach depends on finances, eligibility and long-term plans for the property. Exploring your options early can help your family make a more informed decision while considering the support your loved one needs.
Use Home Equity Without Selling
One approach to financing senior care without a home sale is using some of the property's equity while retaining ownership. Depending on the homeowner's circumstances, possible options include:
- Reverse mortgage: Eligible homeowners may be able to convert part of their home equity into funds. Repayment requirements should be carefully reviewed, particularly when the homeowner moves from the property.
- Home equity line of credit (HELOC): A HELOC lets homeowners borrow against available equity as funds are needed.
- Traditional home equity loan: This option generally provides a lump sum that is repaid through scheduled payments.
These approaches have different eligibility requirements, costs and repayment terms. A qualified financial professional can help families understand how each choice could affect keeping the family home while in assisted living.
Explore Veterans Benefits for Assisted Living
Some veterans and surviving spouses may qualify for benefits that can help with senior living expenses. The Department of Veterans Affairs Aid and Attendance benefit, for example, may provide additional pension payments to eligible individuals who meet specific service, financial and support requirements.
Because eligibility varies, families considering veterans benefits for assisted living should speak with an accredited veterans service officer or other qualified professional before making financial plans.
Walker Place also offers a Military Veterans Program that recognizes those who have served. The community's website notes that its CEO and many team members are U.S. military veterans, bringing a personal connection to this program.
Review Long-Term Care and Life Insurance
Existing insurance coverage may provide another source of funding. Long-term care insurance policies vary significantly, so families should review the benefit amount, elimination period, eligible services and other requirements before relying on a policy.
Other insurance-related assisted living payment options may include:
- Long-term care riders: Certain life insurance policies include riders that may provide funds for eligible long-term support.
- Life settlements: Depending on the policy and circumstances, selling a life insurance policy may provide funds that can be used toward senior living expenses.
An insurance professional can explain the terms of an existing policy and whether these options apply.
Understand Medicaid Assisted Living Coverage in Indiana
Medicaid assisted living coverage is complex, and eligibility and available services depend on state rules and an individual's circumstances. Families should not assume that Medicaid will automatically cover assisted living or that owning a home will automatically prevent eligibility.
Property ownership can also affect future estate recovery considerations. Before transferring assets, changing ownership or making other major financial decisions, consider consulting an Indiana elder law attorney or qualified benefits professional. Early guidance can help families understand current rules and avoid financial decisions that may have unintended consequences.
Consider Rental Income From the Family Home
For some families, renting the house may create income that helps offset monthly senior living expenses while preserving ownership. This can be especially meaningful when keeping the property in the family is a long-term goal.
Families should account for more than expected rent. Property taxes, insurance, repairs, vacancies and management expenses can reduce the income available for Assisted Living. A property manager may also be helpful when relatives cannot manage the home themselves.
Compare the Costs Included in Assisted Living
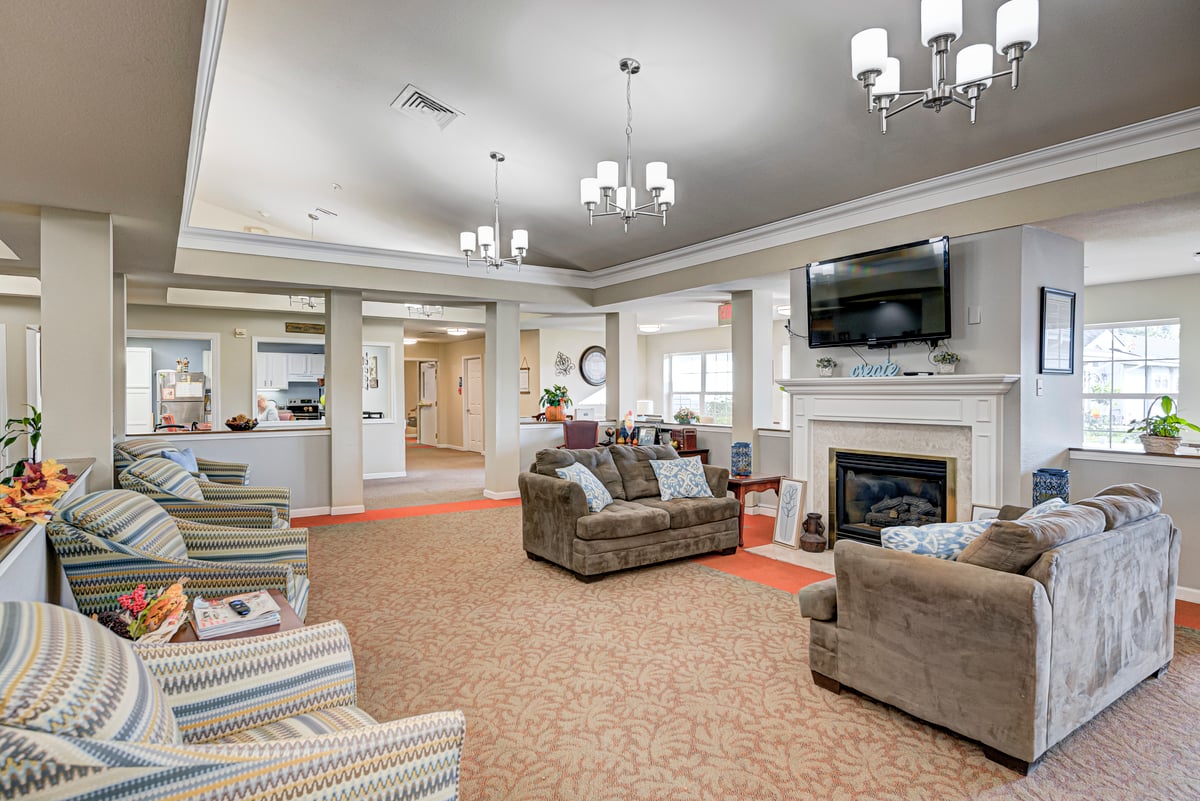
Looking beyond the monthly price can provide a clearer picture of senior living expenses. At Walker Place, Assisted Living includes features such as chef-prepared meals, weekly housekeeping, scheduled transportation and a calendar of programs and events. Residents can choose from suites and one-bedroom apartments with kitchenettes and storage. The community also features gardens and a library, with Intelliplex Medical Center conveniently located across the street.
When comparing the cost of staying at home with senior living, families can consider expenses they already pay separately, such as groceries, home maintenance, transportation and household services. This broader comparison can make monthly budgeting more useful.
Build a Funding Plan That Fits Your Family
There is no single answer for every family. Some may use insurance or veterans benefits, while others combine savings, rental income or home equity. Understanding several approaches to paying for assisted living without selling house assets can make it easier to protect important priorities while planning for a loved one's changing needs.
At Walker Place in Shelbyville, families can explore a comfortable, neighborly setting where residents receive assistance with daily living while staying connected through meals, events and shared spaces.
Schedule a tour of Walker Place to explore Assisted Living, apartment options and community life in Shelbyville.